
What Are Your Chances of Being Audited? IRS Audit Statistics for 2026
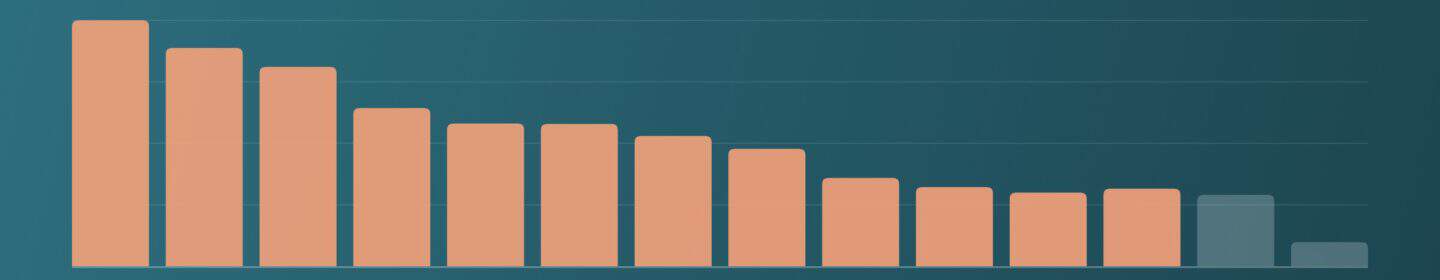
About 3 of every 1,000 individual tax returns filed for tax year 2021 were audited, 510,375 of 161.2 million, or 1 in 316.
For tax year 2010 it was 1 in 99.
This page brings together the official numbers on IRS audits: how often returns are audited, how the odds change with income, how many audits happen by mail, how many end with no change, what they bring in and how the IRS workforce that does them has changed.
Every figure comes from the IRS Data Book, the Treasury Inspector General for Tax Administration, the Government Accountability Office or another government source, and the rates by income are built from the raw IRS tables.
Key Findings
- 1 in 316 individual returns for tax year 2021 were audited (0.32%), down from 1 in 99 for tax year 2010.
- 6.6% of returns with total positive income of $10 million or more were audited for tax year 2021, the highest rate of any income group, down from 21.5% for tax year 2010.
- 0.7% of returns claiming the earned income tax credit were audited for tax year 2021, a higher rate than returns with $500,000 to $1 million in income (0.6%).
- 89.2% of the 441,578 individual audits closed in fiscal year 2025 were done by mail, and field audits have fallen 48% since fiscal year 2020.
- 42.9% of audits of $10 million-plus earners for tax year 2019 ended with no change to the tax owed, compared with 9.9% of audits of filers with income under $25,000.
- $26.8 billion in additional tax was recommended by the 497,621 audits the IRS closed in fiscal year 2025, with 47% of it disputed by the taxpayer.
- 8,609 revenue agents were on the IRS payroll on September 30, 2025, down 20% in one year and barely above the fiscal year 2019 low of 8,526.
- 987,460 CP2000-style underreporter cases were closed in fiscal year 2025, twice the number of individual audits, with $5.9 billion assessed.
Table of Contents
What Are the Odds of Being Audited?
The IRS measures audit coverage by tax year: the number of returns filed for a year that were audited, closed or still open, divided by all returns filed for that year.
For tax year 2021, the most recent year the IRS considers outside the normal three-year audit window, 510,375 of 161,206,833 individual returns had been audited, a coverage rate of 0.32%.
That works out to about 1 in 316 returns.
For tax year 2010 the rate was 1.01%, or 1 in 99, so the odds of an audit have fallen by about two thirds in little more than a decade.
Tax year 2019, the last year before the pandemic, came in at 0.32% as well.
The Government Accountability Office reached the same conclusion in 2022, reporting that the audit rate fell from 0.9% for tax year 2010 to 0.25% for tax year 2019 and that it fell most for taxpayers with incomes of $200,000 and above.
View the data
| Tax year | Returns filed | Audits closed | Audits open | Audit rate | Odds |
|---|---|---|---|---|---|
| 2010 | 143,113,663 | 1,435,760 | 3,397 | 1.01% | 1 in 99 |
| 2011 | 145,586,312 | 1,297,031 | 2,857 | 0.89% | 1 in 112 |
| 2012 | 145,143,496 | 1,181,966 | 2,290 | 0.82% | 1 in 123 |
| 2013 | 147,552,433 | 952,374 | 2,795 | 0.65% | 1 in 154 |
| 2014 | 148,796,860 | 865,670 | 3,466 | 0.58% | 1 in 171 |
| 2015 | 150,675,111 | 872,542 | 4,611 | 0.58% | 1 in 172 |
| 2016 | 150,447,029 | 789,900 | 11,360 | 0.53% | 1 in 188 |
| 2017 | 153,062,634 | 721,464 | 12,955 | 0.48% | 1 in 208 |
| 2018 | 153,927,628 | 549,390 | 7,018 | 0.36% | 1 in 277 |
| 2019 | 157,951,815 | 504,465 | 6,583 | 0.32% | 1 in 309 |
| 2020 | 164,511,483 | 488,468 | 6,646 | 0.30% | 1 in 332 |
| 2021 | 161,206,833 | 498,386 | 11,989 | 0.32% | 1 in 316 |
| 2022* | 161,666,477 | 421,832 | 50,781 | 0.29% | 1 in 342 |
| 2023* | 160,934,651 | 119,805 | 39,461 | 0.10% | 1 in 1,010 |
Why the newest years look low: the IRS generally has three years from the filing date to start an audit.
For tax year 2023, returns filed in 2024, only 0.10% had been audited by September 30, 2025, but that figure will climb for two more years.
We use tax year 2021 as the latest reliable year, as the IRS does.
Free Consultation
Not sure what to do next? Get a straight answer from a tax pro.
Talk to a tax expert — free, no obligation. We’ve resolved over $20 million in IRS debt for our clients.
IRS Audit Rates by Income
The odds rise sharply at the very top and are higher at the very bottom than in the middle.
For tax year 2021, 6.6% of returns with total positive income of $10 million or more were audited, and 3.9% of returns with $5 million to $10 million.
Returns with no positive income, a group that includes filers whose business or investment losses wiped out their income, were audited at 1.8%.
Between $50,000 and $500,000 the rate was about 0.2%, or roughly 1 in 600.
Returns with $1 to $25,000 of income were audited at 0.5%, more than twice the rate for middle incomes, a gap the Government Accountability Office has linked to audits of the earned income tax credit.
A return claiming the earned income tax credit had a 0.7% chance of audit, higher than a return with $500,000 to $1 million of income (0.6%) and more than four times the rate for filers earning $50,000 to $200,000.
Total positive income is the IRS measure that adds up all positive income items on a return before losses, so a filer with $300,000 of wages and a $300,000 business loss still lands in the $200,000 to $500,000 group.
View the rates for tax years 2010, 2019, 2021 and 2022
| Total positive income | Returns filed (TY2021) | Audited (TY2021) | Rate TY2019 | Rate TY2021 | Rate TY2022* | Rate TY2010 |
|---|---|---|---|---|---|---|
| No positive income | 2,931,717 | 54,094 | 5.6% | 1.8% | 0.74% | 20.6% |
| $1 to $25K | 44,983,091 | 227,506 | 0.44% | 0.51% | 0.49% | 1.0% |
| $25K to $50K | 37,679,393 | 82,905 | 0.21% | 0.22% | 0.28% | 0.61% |
| $50K to $75K | 23,132,910 | 34,900 | 0.19% | 0.15% | 0.11% | 0.69% |
| $75K to $100K | 14,828,621 | 22,920 | 0.19% | 0.15% | 0.08% | 0.65% |
| $100K to $200K | 24,900,466 | 40,069 | 0.21% | 0.16% | 0.09% | 0.85% |
| $200K to $500K | 9,597,600 | 21,062 | 0.26% | 0.22% | 0.35% | 2.3% |
| $500K to $1M | 1,779,838 | 10,645 | 0.77% | 0.60% | 1.4% | 3.6% |
| $1M to $5M | 867,592 | 8,174 | 1.8% | 0.94% | 1.9% | 8.2% |
| $5M to $10M | 71,862 | 2,771 | 3.4% | 3.9% | 4.9% | 13.5% |
| $10M or more | 51,250 | 3,375 | 11.5% | 6.6% | 6.6% | 21.5% |
| Returns claiming the EITC | 32,216,183 | 224,123 | 0.79% | 0.70% | 0.75% | 1.8% |
| All individual returns | 161,206,833 | 510,375 | 0.32% | 0.32% | 0.29% | 1.0% |
The gap between the top and the middle used to be far wider.
For tax year 2010, 21.5% of returns with $10 million or more of income were audited, along with 8.2% of returns with $1 million to $5 million.
By tax year 2021 those rates were 6.6% and 0.9%.
Tax years 2022 and 2023 are still inside the normal three-year window for starting an audit, so their rates will rise as the IRS opens more cases.
Download the data by income and tax year (CSV)
Most IRS Audits Happen by Mail
The IRS closed 441,578 audits of individual returns in fiscal year 2025.
Of those, 393,767, or 89.2%, were correspondence audits, handled entirely by letter, and 47,811 were field audits, conducted in person and generally by a revenue agent or tax compliance officer.
Five years earlier, in fiscal year 2020, 79.5% of individual audits were by mail.
Field audits of individuals fell from 92,795 in fiscal year 2020 to 47,811 in fiscal year 2025, a drop of 48%.
Mail audits dominate at lower incomes: 97.3% of audits of filers with income of $1 to $25,000 were by correspondence, compared with 62% for filers with $1 million to $5 million and 9.4% for filers with $10 million or more.
A correspondence audit usually starts with a letter such as a CP75 or Letter 566, and our guide to what IRS audit mail looks like explains how to tell one from a notice.
A Letter 566 usually comes with Form 14817, the reply cover sheet the IRS wants on top of your response.
View the data
| Fiscal year | Individual audits closed | Field | Correspondence | Share by mail | All audits closed (all return types) | Recommended additional tax (all types) |
|---|---|---|---|---|---|---|
| 2020 | 452,515 | 92,795 | 359,720 | 79.5% | 509,917 | $12.9B |
| 2021 | 659,012 | 99,591 | 559,421 | 84.9% | 738,959 | $26.8B |
| 2022 | 625,973 | 93,537 | 532,436 | 85.1% | 708,309 | $30.2B |
| 2023 | 518,607 | 81,041 | 437,566 | 84.4% | 582,944 | $31.9B |
| 2024 | 444,014 | 60,391 | 383,623 | 86.4% | 505,514 | $29.0B |
| 2025 | 441,578 | 47,811 | 393,767 | 89.2% | 497,621 | $26.8B |
If you have received an audit letter, we know how to deal with this the smart way.
Our audit representation service handles the IRS for you, or you can book a free, confidential consultation or call 866-8000-TAX.
How Often Does an Audit End With No Change?
For tax year 2019, the most recent year with nearly all audits finished, 11.4% of individual audits closed with no change to the tax owed.
The share rises steeply with income.
For filers with income of $10 million or more it was 42.9%, and for filers with $500,000 to $5 million it was about 31%.
For filers with income under $25,000 it was 9.9%, and for returns claiming the earned income tax credit it was 11.0%.
A no-change audit still costs the taxpayer time and often professional fees, and it costs the IRS staff hours that produced no revenue.
The IRS cautions that no-change audits close faster than audits that find something, so the no-change share for recent tax years starts high and falls as the slower cases finish.
What Audits Find
Across all return types, the 497,621 audits closed in fiscal year 2025 recommended $26.8 billion in additional tax.
That is down from $31.9 billion in fiscal year 2023, and the number of audits closed is down 33% from the 738,959 closed in fiscal year 2021.
Recommended tax is what the examiner proposed, not what the IRS collected.
In 12,192 of the fiscal year 2025 audits the taxpayer did not agree, and those cases accounted for $12.6 billion, or 47% of the total.
Individual audits recommended $11.3 billion, an average of $25,634 per audit.
The average ranged from $13,642 for filers with income of $1 to $25,000 to $278,922 for filers with $10 million or more.
Returns with no positive income were 17% of individual audits closed but produced 36% of the recommended tax, $4.0 billion.
Audits can also go the other way: 16,158 audits closed in fiscal year 2025 ended with a refund to the taxpayer, totaling $10.4 billion, $7.8 billion of it to corporations.
View the data
| Total positive income | Audits closed | Recommended additional tax | Per audit | Audits with unagreed tax | Amount unagreed |
|---|---|---|---|---|---|
| No positive income | 75,392 | $4.05B | $53,697 | 1,389 | $303.4M |
| $1 to $25K | 131,153 | $1.79B | $13,642 | 910 | $28.5M |
| $25K to $50K | 85,036 | $1.10B | $12,960 | 868 | $27.6M |
| $50K to $75K | 28,591 | $467M | $16,329 | 492 | $20.0M |
| $75K to $100K | 14,352 | $261M | $18,217 | 405 | $28.9M |
| $100K to $200K | 23,852 | $597M | $25,034 | 979 | $50.9M |
| $200K to $500K | 35,021 | $504M | $14,388 | 1,540 | $88.3M |
| $500K to $1M | 23,004 | $376M | $16,329 | 1,171 | $97.5M |
| $1M to $5M | 14,913 | $659M | $44,195 | 1,087 | $267.1M |
| $5M to $10M | 3,741 | $356M | $95,099 | 256 | $155.1M |
| $10M or more | 4,060 | $1.13B | $278,922 | 312 | $744.8M |
Audits of Corporations, Partnerships and Estates
Audits of the largest corporations used to be nearly universal.
For tax year 2010, 86.7% of corporations with $20 billion or more in assets were audited.
By tax year 2019 the rate was 49.2%, and for tax year 2021 it was 35.9%.
Audit coverage of all corporations other than S corporations fell from 1.6% for tax year 2010 to 0.4% for tax year 2021.
In May 2024 the IRS said it would nearly triple the audit rate on corporations with assets over $250 million to 22.6% by tax year 2026, from 8.8% for tax year 2019.
Our calculation from the latest Data Book puts that group at 9.9% for tax year 2019, 5.9% for tax year 2021 and 4.9% so far for tax year 2022.
Partnerships and S corporations, which pass their income through to their owners, were each audited at about 0.1% for tax year 2021, and estate tax returns at 2.6%.
View the data
| Tax year | Corporations with $20B+ in assets | Audited | Audit rate | All corporations (except S corps) |
|---|---|---|---|---|
| 2010 | 330 | 286 | 86.7% | 1.6% |
| 2011 | 328 | 275 | 83.8% | 1.4% |
| 2012 | 351 | 278 | 79.2% | 1.3% |
| 2013 | 371 | 275 | 74.1% | 1.2% |
| 2014 | 382 | 270 | 70.7% | 1.1% |
| 2015 | 398 | 285 | 71.6% | 1.0% |
| 2016 | 410 | 274 | 66.8% | 0.9% |
| 2017 | 430 | 276 | 64.2% | 0.7% |
| 2018 | 451 | 282 | 62.5% | 0.6% |
| 2019 | 472 | 232 | 49.2% | 0.5% |
| 2020 | 451 | 192 | 42.6% | 0.7% |
| 2021 | 512 | 184 | 35.9% | 0.4% |
| 2022* | 543 | 158 | 29.1% | 0.3% |
| 2023* | 570 | 125 | 21.9% | 0.1% |
Audit coverage by type of return, tax year 2021.
| Type of return | Returns filed | Audited | Audit rate |
|---|---|---|---|
| Individual income tax returns | 161,206,833 | 510,375 | 0.32% |
| Corporations (except S corporations) | 1,557,525 | 6,254 | 0.40% |
| Corporations with $20 billion or more in assets | 512 | 184 | 35.9% |
| Partnerships | 4,467,584 | 5,248 | 0.12% |
| S corporations | 5,120,552 | 6,498 | 0.13% |
| Estate tax returns | 34,367 | 904 | 2.6% |
| Gift tax returns | 448,155 | 535 | 0.12% |
| Employment tax returns | 34,798,162 | 27,110 | 0.08% |
| Excise tax returns | 1,433,708 | 5,192 | 0.36% |
The Checks That Are Not Called Audits
Far more taxpayers hear from the IRS through automated matching than through an audit.
The IRS received 4.47 billion information returns in fiscal year 2025, such as Forms W-2 and 1099, and its Automated Underreporter Program compares them with what people report.
The program closed 987,460 cases in fiscal year 2025, more than twice the number of individual audits, and assessed $5.9 billion in tax and interest.
Most of these cases arrive as a CP2000 notice, which proposes a change and asks the taxpayer to agree or explain.
Case closures were 1,151,873 in fiscal year 2024 and 1,582,131 in fiscal year 2022, when assessments peaked at $8.7 billion.
The Automated Substitute for Return Program, which files a return for people who did not, closed 592,773 cases in fiscal year 2025, 161,908 of them with an actual return prepared, and assessed $2.9 billion (how a substitute for return works).
The IRS also sent 1,440,328 math error notices in fiscal year 2025 to correct arithmetic, eligibility and transcription errors during processing, none of which count as audits.
View the data
| Fiscal year | Cases closed | Additional assessments | Per case |
|---|---|---|---|
| 2019 | 1,968,731 | $6.66B | $3,381 |
| 2020 | 942,155 | $3.92B | $4,162 |
| 2022 | 1,582,131 | $8.73B | $5,517 |
| 2023 | 1,019,050 | $6.59B | $6,466 |
| 2024 | 1,151,873 | $7.65B | $6,644 |
| 2025 | 987,460 | $5.90B | $5,973 |
The IRS Promised More Audits of the Wealthy, Then Lost a Fifth of Its Revenue Agents
In May 2024 the IRS set audit targets for tax year 2026: a 16.5% rate for individuals with total positive income over $10 million, up from 11% for tax year 2019, 22.6% for corporations with assets over $250 million and 1% for partnerships with assets over $10 million.
It also said audit rates would not rise for taxpayers earning under $400,000.
The staff to do that work then shrank.
The IRS had 10,736 revenue agents in pay status on September 30, 2024, and 8,609 a year later, a drop of 20%.
The agency employed 13,879 revenue agents in fiscal year 2010 and 8,526 in fiscal year 2019.
Total IRS employment fell from 99,628 to 80,967 over the same year, down 19%, a decline the Data Book attributes mainly to the deferred resignation, early retirement and separation incentive programs that took effect by September 30, 2025.
The Treasury Inspector General for Tax Administration counted 15,348 examination staff across the IRS at the end of fiscal year 2024, 11,769 at the end of fiscal year 2025 and 10,527 on January 10, 2026, a 31% decline.
TIGTA reported that audits started on individual returns fell 31% from fiscal year 2024 to fiscal year 2025, that audits started on individuals with income over $400,000 fell 27% and that the IRS lost about 27% of its examination and collection staff in that year.
Collection staffing fell the same way, which we track on our tax debt statistics page.
View the data
| As of | Revenue agents | Tax compliance officers | Tax examiners and other | Total |
|---|---|---|---|---|
| FY2023 | 7,902 | 594 | 3,282 | 11,778 |
| FY2024 | 10,778 | 542 | 4,028 | 15,348 |
| FY2025 | 8,491 | 410 | 2,868 | 11,769 |
| Jan. 2026 | 7,726 | 318 | 2,483 | 10,527 |
View the data
| Tax year | Returns with $10M+ income | Audited | Audit rate |
|---|---|---|---|
| 2010 | 13,322 | 2,862 | 21.5% |
| 2011 | 13,846 | 2,505 | 18.1% |
| 2012 | 20,287 | 2,763 | 13.6% |
| 2013 | 15,151 | 1,799 | 11.9% |
| 2014 | 19,447 | 1,905 | 9.8% |
| 2015 | 21,149 | 2,008 | 9.5% |
| 2016 | 18,947 | 1,684 | 8.9% |
| 2017 | 23,475 | 1,751 | 7.5% |
| 2018 | 26,517 | 2,806 | 10.6% |
| 2019 | 24,457 | 2,824 | 11.5% |
| 2020 | 30,646 | 2,733 | 8.9% |
| 2021 | 51,250 | 3,375 | 6.6% |
| 2022* | 42,191 | 2,773 | 6.6% |
| 2023* | 36,697 | 1,892 | 5.2% |
Audits of the Earned Income Tax Credit
The earned income tax credit goes to working people with low and moderate incomes, and its audits are a large share of all audits.
In fiscal year 2025 the IRS closed 93,857 audits of returns claiming the credit, 21% of all individual audits, and 98.9% of them were done by mail.
Those audits recommended an average of $6,176 in additional tax, the lowest of any group on this page.
EITC audits are falling fast: there were 277,936 in fiscal year 2021 and 167,091 in fiscal year 2024, so the fiscal year 2025 count is down 44% in one year and 66% in four.
For tax year 2021, 0.7% of returns claiming the credit were audited, compared with 1.8% for tax year 2010.
The National Taxpayer Advocate reported that of nearly 260,000 EITC audits closed in fiscal year 2022, 38% ended because the taxpayer never responded and 25% ended in default, while 18% ended with no change.
The same report found that 55% of the audited EITC returns had been prepared by a paid preparer, but only 3% of those taxpayers had professional representation during the audit.
View the data
| Fiscal year | EITC audits | Other individual audits | EITC share |
|---|---|---|---|
| 2020 | 157,803 | 294,712 | 34.9% |
| 2021 | 277,936 | 381,076 | 42.2% |
| 2022 | 254,980 | 370,993 | 40.7% |
| 2023 | 229,645 | 288,962 | 44.3% |
| 2024 | 167,091 | 276,923 | 37.6% |
| 2025 | 93,857 | 347,721 | 21.3% |
Still have questions? Talk to a tax expert — free.
Methodology and Definitions
Every figure on this page comes from a primary U.S. government source: the IRS Data Book, IRS news releases, the Treasury Inspector General for Tax Administration, the Government Accountability Office and the National Taxpayer Advocate.
Nothing is taken from surveys, private datasets or other statistics roundups.
Where we calculated a figure rather than quoting one, the calculation is described below.
Definitions
- Audit (examination). An IRS review of a filed return to verify income, deductions and credits. The IRS counts a distinct taxpayer once per tax year and form type.
- Audit rate (coverage). Audits closed plus audits still open for a tax year, divided by all returns filed for that tax year, as of September 30, 2025. This is the IRS Data Book definition.
- Total positive income (TPI). The sum of all positive income items on an individual return, before losses. The Data Book groups individual returns by TPI, not adjusted gross income.
- Correspondence audit. An audit conducted by mail. A field audit is generally conducted in person by a revenue agent, tax compliance officer, tax examiner or revenue officer examiner.
- No-change audit. An audit closed without any adjustment to the tax owed.
- Recommended additional tax. The additional tax the examiner proposed when the audit closed, before any appeal. It is not the amount collected.
- Unagreed. A closed audit in which the taxpayer did not agree to the recommended tax.
- Revenue agent. The IRS job series that conducts field audits of complex returns. Tax compliance officers conduct office audits and tax examiners handle correspondence audits.
Calculations
- Audit rate: audits closed plus audits in process, divided by returns filed, from Table 3-1. Our figures match the rounded percentages the IRS publishes.
- Odds (1 in X): returns filed divided by audits.
- Share by mail: correspondence audits divided by all audits closed, from Table 3-2.
- No-change rate: audits closed with no change divided by audits closed, from Table 3-1.
- Recommended tax per audit: recommended additional tax divided by audits closed, from Table 3-2.
- Corporations with assets over $250 million: the five Table 3-1 asset classes from $250 million up, combined.
Tax Years, Fiscal Years and Snapshots
Audit rates are by tax year, meaning the year the return covers, and are a snapshot as of September 30, 2025.
The IRS generally has three years from the filing date to start an audit, so rates for tax years 2022 and 2023 will rise.
Tax years 2010 to 2014 come from the IRS all-years file and are as of September 30 of 2020 through 2024, when each year last appeared in the Data Book.
Counts of audits closed, recommended tax, underreporter cases and staffing are by federal fiscal year, which runs from October 1 to September 30.
The Data Book suppresses a few cells to protect taxpayer privacy; where a component was suppressed we used the percentage the IRS published.
What This Page Does Not Claim
- Audit rates by state, because the IRS does not publish them.
- Audit rates by adjusted gross income, because the Data Book groups individual returns by total positive income.
- How much of the recommended tax the IRS collected, because the Data Book does not report collections by audit.
- Why any particular return was selected. The IRS says it uses computerized screening, random sampling and audits of related returns, but it does not publish its selection rules.
Sources
- Internal Revenue Service, IRS Data Book, Fiscal Year 2025 (June 2026), Table 3-1, Examination coverage and recommended additional tax after examination, by type and size of return, tax years 2015 to 2023, and the all-years file covering tax years 2010 to 2023. irs.gov.
- Internal Revenue Service, IRS Data Book, Table 3-2 (fiscal year 2025) and Table 18 (fiscal years 2020 to 2024), Examination coverage: recommended additional tax and returns with unagreed additional tax, by type and size of return. irs.gov.
- Internal Revenue Service, IRS Data Book, Fiscal Year 2025, Table 3-4, Returns examined resulting in refunds. irs.gov.
- Internal Revenue Service, IRS Data Book, Information Reporting Program, Table 3-8 (fiscal year 2025) and the corresponding tables in the 2019 to 2024 editions. irs.gov.
- Internal Revenue Service, IRS Data Book, Fiscal Year 2025, Table 3-9, Math errors on individual income tax returns. irs.gov.
- Internal Revenue Service, IRS Data Book, Fiscal Year 2025, Table 6-3, Personnel summary, by employment status, budget activity and selected personnel type. irs.gov.
- Treasury Inspector General for Tax Administration, Trends in Compliance Activities Through Fiscal Year 2025, report 2026-3S0-045 (August 26, 2026). tigta.gov.
- Internal Revenue Service, IR-2024-130, IRS releases Strategic Operating Plan update (May 2, 2024). irs.gov.
- U.S. Government Accountability Office, Tax Compliance: Trends of IRS Audit Rates and Results for Individual Taxpayers by Income, GAO-22-104960 (May 17, 2022). gao.gov.
- National Taxpayer Advocate, EITC Audits: What You Need to Know, NTA Blog (August 17, 2023). taxpayeradvocate.irs.gov.
How to Cite This Page
Journalists, researchers and educators may republish any chart, table or figure on this page without asking.
Please credit Choice Tax Relief and link to this page so readers can reach the sources and methodology.
Allec, Logan. “What Are Your Chances of Being Audited? IRS Audit Statistics for 2026.” Choice Tax Relief, updated October 2, 2026. https://choicetaxrelief.com/tax-statistics/irs-audit-statistics/Need a figure cut a different way, the underlying spreadsheet, or a CPA to interview?
Email Logan Allec, CPA at [email protected].
We update this page each June, when the IRS releases its annual Data Book, and when TIGTA publishes its annual compliance trends report.
See all of our studies on the tax statistics page, including how many Americans owe the IRS and the average tax refund.
Frequently Asked Questions About IRS Audits
What are the chances of being audited by the IRS?
About 1 in 316. For tax year 2021, the latest year the IRS treats as complete, 0.32% of individual returns were audited, according to the IRS Data Book. The rate was 1.01%, or 1 in 99, for tax year 2010.
What income level gets audited the most?
Returns with total positive income of $10 million or more, which were audited at 6.6% for tax year 2021. Returns with $5 million to $10 million were audited at 3.9%, and returns with no positive income at 1.8%. Returns with $50,000 to $500,000 were audited at about 0.2%.
Are most IRS audits done by mail?
Yes. Of the 441,578 individual audits the IRS closed in fiscal year 2025, 89.2% were correspondence audits handled by letter. For filers with income under $25,000 the share was 97.3%.
How many IRS audits end with no change?
For tax year 2019, 11.4% of individual audits closed with no change to the tax owed. The share was 42.9% for filers with income of $10 million or more and 9.9% for filers with income under $25,000.
How far back can the IRS audit you?
Generally three years from the date you filed. The window is six years if you left out more than 25% of your gross income, and there is no time limit if you never filed or filed a fraudulent return. See our guide to the IRS statute of limitations.
How many revenue agents does the IRS have?
The IRS had 8,609 revenue agents in pay status on September 30, 2025, down from 10,736 a year earlier, according to the IRS Data Book. It employed 13,879 revenue agents in fiscal year 2010.
Is a CP2000 notice an audit?
No. A CP2000 comes from the Automated Underreporter Program, which matches W-2s, 1099s and other information returns against your tax return and proposes a change. The program closed 987,460 cases in fiscal year 2025, more than twice the number of individual audits, but the IRS does not count them as audits.
Get Help Now
Not sure what to do next? Get a straight answer from a tax pro.
Talk to a tax expert — free, no obligation. We’ve resolved over $20 million in IRS debt for our clients.


Author:

Logan Allec, CPA, Founder and Owner
Logan Allec has been serving taxpayers as a CPA for over 14 years. After leaving his role at a "Big 4" firm, he started Choice Tax Relief to help everyday Americans who have found themselves behind on their taxes. He also educates thousands of people daily about tax relief on his YouTube channel. In addition to his CPA license, Logan also has a Master's Degree in Taxation from the University of Southern California (USC). He lives with his wife and children in the Los Angeles area. Learn more about Logan here.